Quick Summary:
- LDW may cover storm damage, but flood immersion is often excluded.
- Ask for written LDW terms, not only a verbal summary.
- Check exclusions for water damage, negligence, restricted areas, and ignored warnings.
- Document the car condition, parking location, and weather alerts if storms hit.
When you are arranging car hire in Florida, it is smart to think about tropical storms, hurricanes, and flooding before you pick up the keys. Many travellers assume Loss Damage Waiver (LDW) is a blanket promise that any damage is waived. In practice, LDW is a contract with defined limits, exceptions, and conditions. Whether hurricane or flood damage is covered depends on how the event happened and what the agreement says, not simply the label of the weather event.
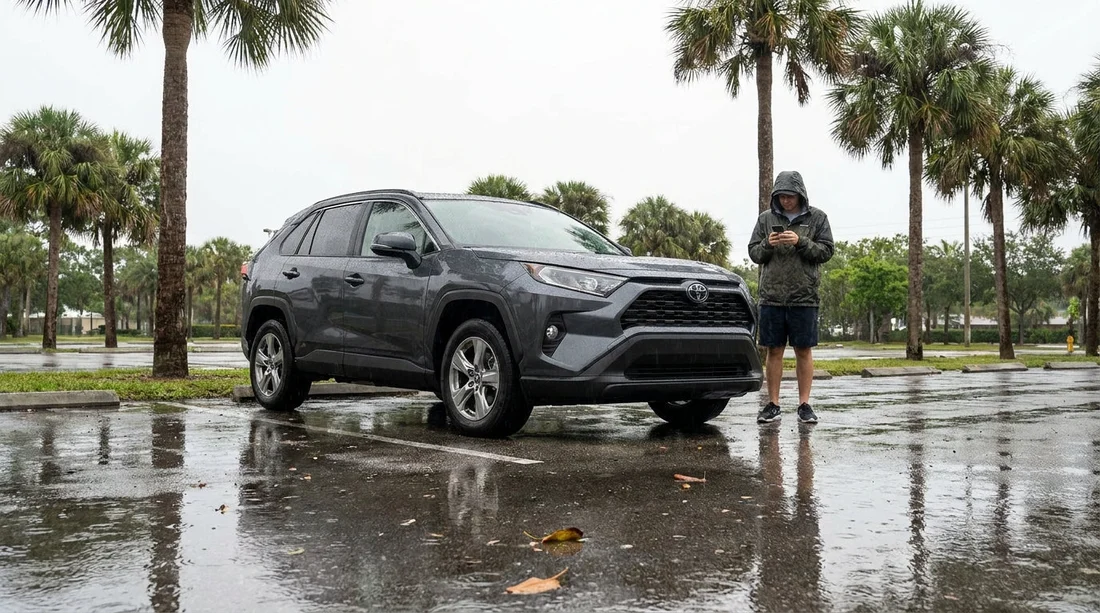
Florida’s storm season creates a common real world scenario: you park at a hotel, a storm surge reaches the car, and the vehicle is later declared a total loss. Another scenario is wind driven debris damages bodywork, glass, or roof panels. These two outcomes can be treated very differently under LDW. Understanding the typical approach helps you make better decisions at the counter, and avoid surprises after a claim.
What LDW usually means in Florida car hire
LDW is generally a waiver, not traditional insurance. It commonly reduces or removes your financial responsibility for damage to, or theft of, the rental vehicle, as long as you follow the rental agreement. Some rentals include a basic LDW option, others offer it as an add on at the counter, and terms vary by supplier.
LDW often focuses on collision or loss type outcomes, such as scraping a bumper, a car park ding, or theft. Storm related damage can fall under general damage to the vehicle, but many contracts treat flood, water, or driving into hazardous conditions separately. This is why reading the actual exclusions matters more than the marketing name.
If you are collecting near major hubs, you may see slightly different documentation packs and add on menus. For example, a pick up near Miami Airport might present supplier specific LDW wording that differs from a city location, even within the same brand family. The only safe assumption is that each agreement must be checked on its own terms.
Does LDW cover hurricane damage?
Hurricane damage is not one single category. LDW may respond differently depending on the mechanism of loss.
Wind and debris damage is sometimes treated like any other physical damage to the vehicle. If a branch falls on the bonnet, or flying debris cracks a windscreen, LDW may apply, provided you complied with the agreement and did not act negligently.
Storm surge and standing water can be treated as flood or water damage. Many rental agreements exclude water immersion, saltwater damage, or any damage caused by driving into water, even if the wider cause is a hurricane. If the car is submerged or the engine is hydrolocked, suppliers may argue the proximate cause is flood or water, which can fall under an exclusion.
Negligence clauses are a frequent pivot point. Even when storm is not excluded, you may be held responsible if the supplier decides you ignored warnings, drove around road closures, entered restricted areas, or failed to take reasonable precautions, such as parking in a safer location when a major storm warning is active.
During hurricane watches and warnings, some suppliers also introduce operational restrictions. You may be told not to drive, to keep the car off barrier islands, or to follow evacuation instructions. If damage occurs while you are breaching a restriction, LDW can be voided.
Does LDW cover flood damage?
Flood damage is the area where travellers most often face exclusions. Many agreements distinguish between accidental damage and water related damage, and flood is frequently carved out. Common examples include water immersion, including saltwater, brackish water, or freshwater that enters the engine, electrical systems, or cabin. Another common example is driving through standing water or into an area with visible flooding, because some suppliers treat any water ingestion as avoidable.
However, not every contract excludes flood in the same way. Some waive damage unless an excluded action occurred, others explicitly exclude flood, water, or act of nature events. This is why you should request the written terms for the exact LDW product you are accepting, including the fine print on exclusions and voiding conditions.
Common LDW exclusions and void triggers to look for
Before you accept LDW at the counter during car hire in Florida, scan for these recurring issues that affect hurricane and flood claims: acts of nature wording, water damage wording, negligence and reasonable care clauses, and any special restrictions during warnings or declared emergencies.
Use restrictions still deserve extra attention. Check where you are allowed to drive and park, because barrier islands, beaches, unpaved roads, or certain zones may be restricted, and storms can worsen the risk. If you are visiting Orlando then driving to the coast, pick up terms can vary between an Orlando Airport collection and another location, so confirm the route is permitted.
Administrative fees can still apply even when LDW responds. Depending on wording, you may face loss of use, administrative fees, towing, or diminished value. If these are not waived, a storm incident can still generate a significant bill.
What to confirm at the counter, before you agree to cover
Counter discussions can be fast, especially at busy Florida locations. The goal is to leave with no ambiguity about how storm and flood losses are treated.
Ask for the LDW terms in writing. You want the actual product description and exclusions for the supplier you are renting from, not a generic summary. If the representative explains it verbally, compare their explanation to the text.
Clarify storm versus flood treatment. Ask: “If the vehicle is damaged by wind blown debris during a hurricane warning, does LDW apply?” Then ask a separate question: “If the vehicle is damaged by standing water or storm surge, is that excluded?” Keep the questions distinct.
Match your plans to your vehicle choice. If you expect heavy rain and family travel, consider the practicalities of where you will park and what you will carry. For larger groups in storm season, choosing something suitable through a minivan rental near Disney in Orlando can help keep luggage and passengers protected, but it does not change water damage exclusions. The contract language remains the key factor.
If a storm hits during your Florida trip
How you behave during and after a storm can affect whether LDW remains valid. Avoid driving into flooded roads, and park away from low lying areas and coastal surge zones if it is safe and permitted. Take photos of where the car was parked and any visible damage when it is safe, and report incidents using the steps in your rental agreement.
If you picked up through a location like Fort Lauderdale Airport, keep those contact details accessible because storm disruption can affect phone service and travel plans.
How to think about cover when comparing options
The word cover gets used loosely in car hire. With LDW, you are really evaluating what is waived, when it is waived, and what voids it. For storm and flood events in Florida, the key questions are about water damage exclusions, negligence language, and compliance with warnings and restrictions.
Also remember that different products can overlap. A rental may include basic protection, then offer a higher tier LDW, and possibly other items. You do not need to buy everything, but you do need to know which gaps matter for a hurricane prone destination. If your travel includes urban areas where flash flooding can occur, ensure you are comfortable with the water related wording in the agreement you accept, regardless of whether you collect near Miami Airport with Alamo or elsewhere.
FAQ
Is flood damage normally included with LDW in Florida?
Often it is not. Many rental agreements exclude flood, water immersion, storm surge, or damage caused by driving through standing water, even if LDW covers other types of damage.
If a hurricane damages the car while it is parked, will LDW apply?
It can, especially for wind or debris damage, but it depends on exclusions and whether the supplier believes reasonable care was taken. If the damage is from storm surge or flooding, exclusions are more likely.
Can LDW be voided if I drive during a hurricane warning?
Yes, potentially. If the agreement includes restrictions, road closure compliance, or reasonable care requirements, driving into hazardous conditions can be treated as a breach that voids LDW.
What charges might I still pay even if LDW applies?
Depending on the terms, you might still see fees such as towing, administrative charges, or loss of use. Confirm in writing what LDW waives, and what it does not.
What is the single most important thing to check before I accept LDW?
Read the written exclusions for water and acts of nature wording, then ask the counter to confirm how flood and storm surge are treated under that specific LDW product.